Owning a home is still one of the most reliable ways Americans build long-term wealth — but for a first-time buyer, the mortgage process can feel like it's written in another language. APRs, points, PMI, escrow, underwriting… the jargon comes at you fast. The truth is that buying a home is simply a sequence of small, very doable steps. Here is the entire journey, laid out in plain English.
Know What You Can Comfortably Afford
Start with a budget, not a listing site. A useful rule of thumb is the 28/36 rule: keep your total housing payment — principal, interest, property taxes, insurance, and any HOA fees — under about 28% of your gross monthly income, and your total debt payments under 36%. Lenders will often approve you for more than this, but "approved for" and "comfortable with" are very different numbers. Build in room for maintenance, utilities, and the surprises every homeowner eventually meets.
Get Your Credit Mortgage-Ready
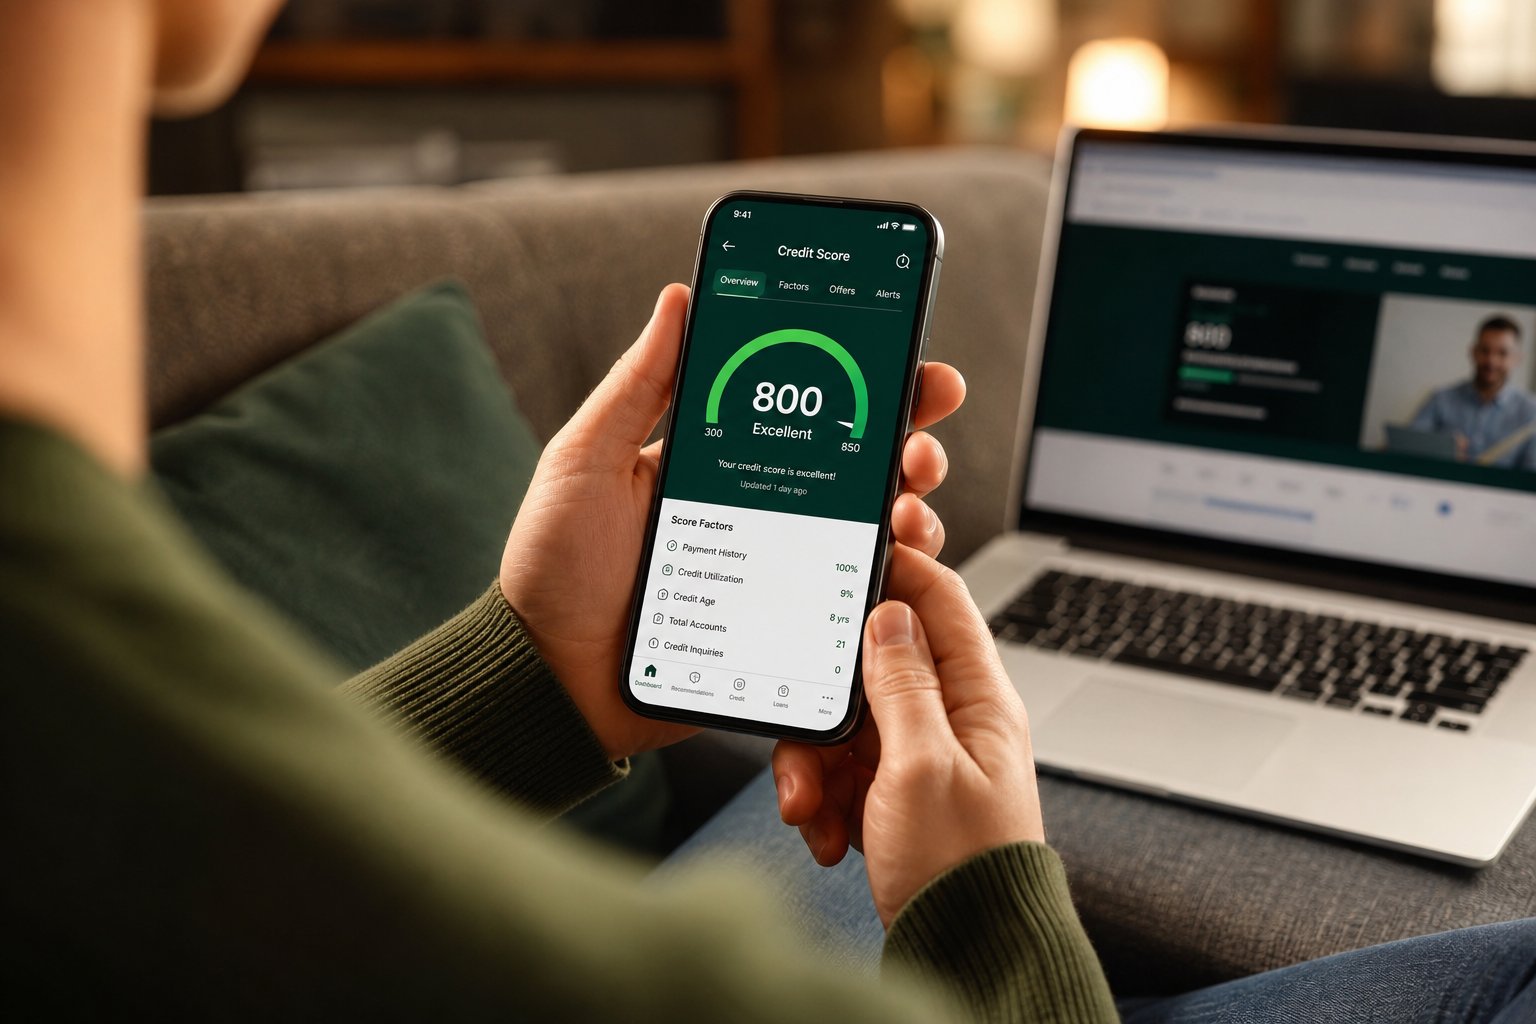
Months before you start touring homes, get your credit in shape. Conventional loans typically want a 620 minimum score, FHA loans can go as low as 580 (sometimes 500 with a larger down payment), and the best rates generally go to borrowers above 740. Pay down credit card balances, dispute any errors on your credit reports, and avoid new credit applications while you're house hunting. Even a 20-point improvement can meaningfully lower your rate.
Save for the Down Payment — But Don't Assume 20%
The 20% down payment is one of the most persistent myths in home buying. FHA loans require as little as 3.5% down, VA and USDA loans can require nothing at all, and many conventional programs accept 3–5%. What 20% buys you is no private mortgage insurance (PMI) and a smaller loan — but waiting years to save it while prices and rates move can cost more than the PMI would. Also budget for closing costs, typically 2–5% of the purchase price, and ask your lender about state and local first-time buyer assistance programs; many offer grants or forgivable loans.
The best time to start preparing for a mortgage isn't when you find the house — it's the year before.
Understand the Main Loan Types
Fixed-rate mortgages keep the same interest rate for the life of the loan — the 30-year fixed is the most popular because it keeps payments predictable, while the 15-year fixed builds equity much faster at lower rates but with higher payments. Adjustable-rate mortgages (ARMs) start with a lower fixed rate for 5, 7, or 10 years and then adjust — sensible if you plan to sell or refinance before the adjustment, risky otherwise. Beyond that, FHA loans are friendlier to lower credit scores and smaller down payments, VA loans offer outstanding terms to eligible veterans and service members, and conventional loans are the flexible standard. The right choice depends on your timeline, credit, and cash — not on what worked for your neighbor.
Get Pre-Approved Before You Shop
Pre-qualification is an estimate based on what you tell a lender; pre-approval is a conditional commitment based on documents they've verified — pay stubs, tax returns, bank statements. In competitive markets, sellers take pre-approved buyers seriously and often won't consider offers without one. Pre-approval also gives you a firm budget ceiling, which keeps you from falling in love with a house you can't finance.
Compare Lenders — Rates Vary More Than You Think
Interest rates and fees differ surprisingly widely between lenders, even for the same borrower on the same day. Collect Loan Estimates from at least three lenders — the format is standardized by law, which makes comparing rates, points, and fees straightforward. Once you've chosen, you can usually lock your rate for 30–60 days while you close, protecting you from mid-process rate hikes. And whatever you do, don't open new credit accounts or make large purchases during escrow; lenders re-check your credit right before closing.
From Accepted Offer to Closing Day
After your offer is accepted, the machinery takes over: the home inspection reveals the property's true condition, the appraisal confirms its value for the lender, and underwriting verifies every document in your file. You'll do a final walkthrough a day or two before closing to confirm agreed repairs were made and the home is in the promised condition. You'll receive the Closing Disclosure at least three business days before signing — read it carefully and compare it to your Loan Estimate. One modern warning: wire fraud increasingly targets homebuyers, so always verify wiring instructions by phone using a number you look up independently, never one from an email.
None of these steps is difficult on its own — the challenge is simply knowing the order and preparing ahead of time. First-time buyers who start preparing a year early routinely save thousands compared to those who improvise. Our Mortgage Loan specialists at Loan Credit Network walk first-time buyers through every stage, from the first budget conversation to the day the keys land in your hand.