Your credit score is one of the most powerful numbers in your financial life. It decides whether you qualify for a mortgage, how much interest you pay on a car loan, which credit cards welcome you, and sometimes even how much you pay for insurance or whether a landlord approves your rental application. Yet millions of Americans never check their score, and far fewer understand what actually moves it. The good news is that no matter where your score stands today, a handful of deliberate, consistent habits can lift it meaningfully within six to twelve months.
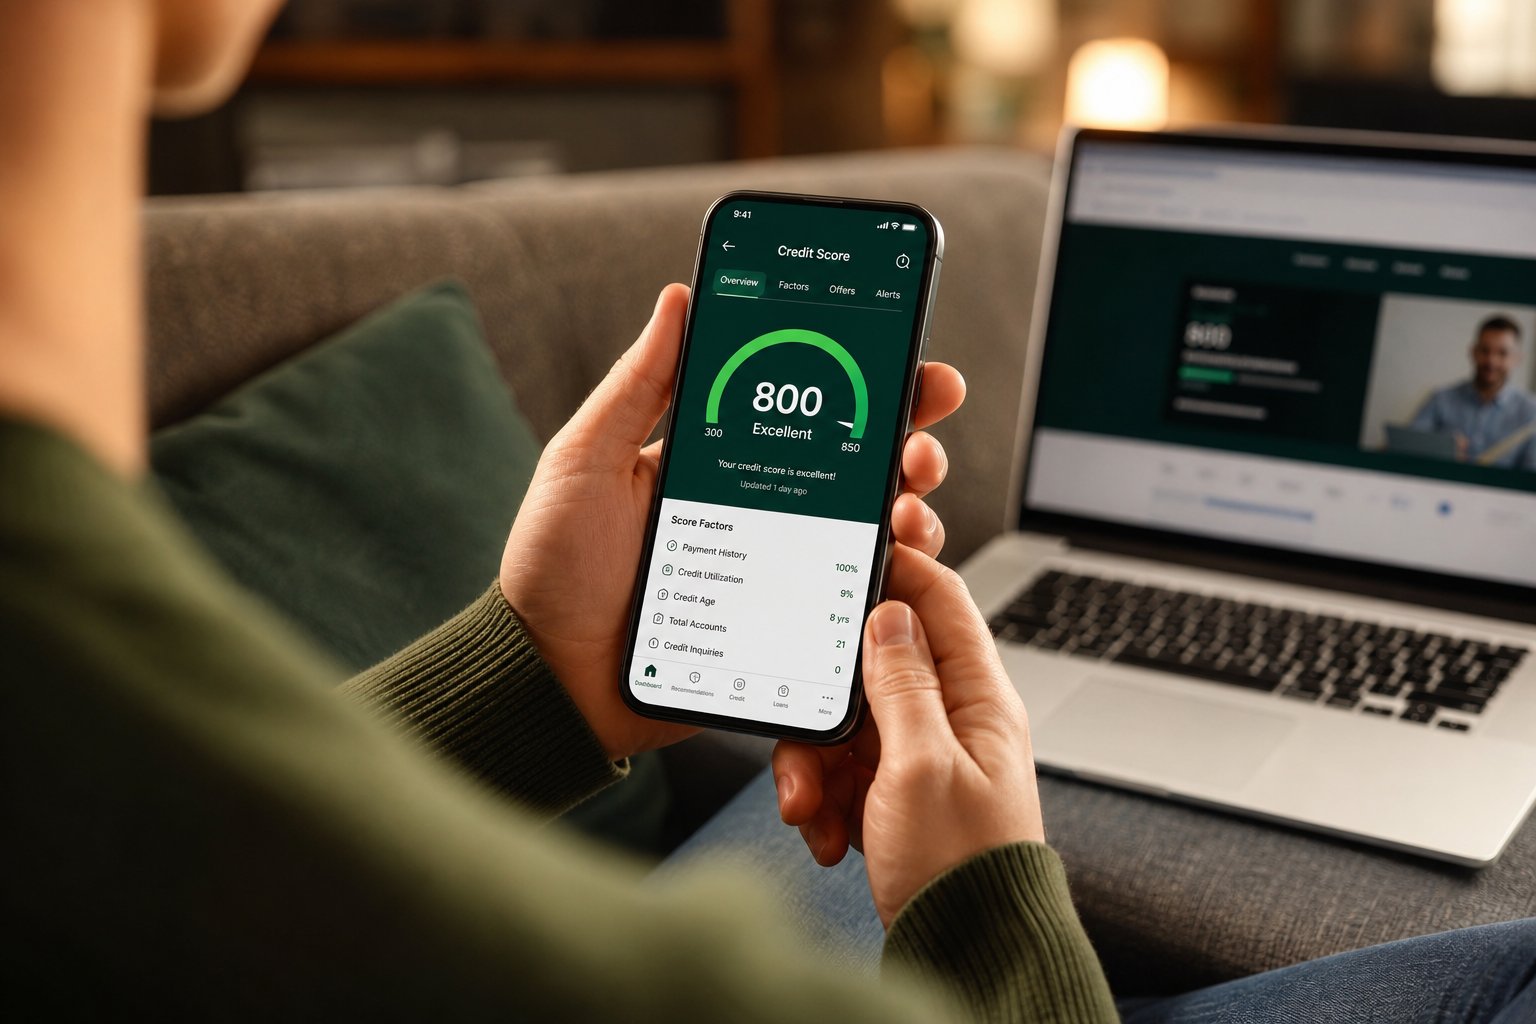
Before you can improve your credit score, you need to understand what's behind it. Most lenders rely on FICO scores, which are built from five ingredients: payment history (35% of your score), amounts owed (30%), length of credit history (15%), new credit (10%), and credit mix (10%). Those weightings tell you exactly where to focus. Two missed payments can do far more damage than ten new applications, and lowering your utilization ratio often produces faster results than anything else you can do.
Protect Your Payment History — First
Payment history is the single biggest factor in your score, so nothing matters more than paying every bill on time. Set up autopay for at least the minimum due on all credit accounts, then layer on calendar reminders as a safety net. If you've missed payments in the past, get current and stay current — the older a missed payment gets, the less it weighs on your score. And if you have a generally clean record with one accidental slip, a polite goodwill letter to the lender asking them to remove it often works better than people expect.
Master Your Credit Utilization
Credit utilization — the percentage of your available credit you're actually using — is the fastest lever you can pull. Aim to keep every card below 30% of its limit, and ideally under 10%. Two tricks make this easier than it sounds: pay your balance down before your statement closing date (not just the due date), because that's the balance most issuers report to the bureaus, and request credit limit increases you don't intend to spend. A $900 balance on a $1,000 limit reads as 90% utilization; the same balance on a $3,000 limit reads as 30%.
Improving your credit isn't about tricks — it's about giving the bureaus six straight months of proof that you can be trusted.
Think Twice Before Closing Old Accounts
Closing an old credit card can quietly hurt your score in two ways: it shortens your average credit history, and it shrinks your total available credit, which automatically pushes your utilization ratio up. Unless a card carries an annual fee you no longer justify, keep it open. Put one small recurring charge on it — a streaming subscription or a phone bill — and pay it in full each month so the issuer never closes it for inactivity.
Go Easy on New Applications
Every hard inquiry can shave a few points off your score, and a burst of applications signals risk to lenders. In the months before a major loan application such as a mortgage, avoid opening new credit cards entirely. One important exception: when you're rate-shopping for a mortgage, auto loan, or student loan, multiple inquiries within a short window — typically 14 to 45 days — are counted as a single inquiry, so comparing lenders doesn't have to cost you.
Audit Your Credit Reports for Errors
Errors on credit reports are more common than most people realize: accounts that don't belong to you, balances reported incorrectly, or debts you already paid off still showing as outstanding. You're entitled to free weekly credit reports from all three bureaus — Equifax, Experian, and TransUnion — through annualcreditreport.com. Pull them, read them line by line, and dispute anything inaccurate directly with the bureau. Removing a single wrongly reported delinquency can move your score up dramatically.
Build Healthy Habits — and Be Patient
Beyond the big levers, a healthy credit mix — a blend of revolving credit and an installment loan like a car payment — helps your score over time, but never take out a loan just to game the system. What actually works is boringly consistent: six to twelve months of on-time payments, low balances, and no unnecessary applications. Scores don't jump overnight, but they climb steadily for anyone who gives the bureaus a steady stream of good behavior to report.
Your credit score isn't a mystery or a fixed label — it's a running record of habits, and habits can change. Every point you gain translates into real money: on a $300,000 mortgage, the difference between a fair score and an excellent one can mean tens of thousands of dollars in interest. If you'd like a personalized plan for your credit situation, our Credit Loan specialists at Loan Credit Network review your profile for free and map out the fastest realistic path to a stronger score.